Impact of Government Organizational Reform to Research Legal System and Response Thereto (2) – Observation of the Swiss Research Innovation System
Impact of Government Organizational Reform to Research Legal System and Response Thereto (2) – Observation of the Swiss Research Innovation System
I. Foreword
Switzerland is a landlocked country situated in Central Europe, spanning an area of 41,000 km2, where the Alps occupy 60% of the territory, while it owns little cultivated land and poor natural resources. In 2011, its population was about 7,950,000 persons[1]. Since the Swiss Federal was founded, it has been adhering to a diplomatic policy claiming neutrality and peace, and therefore, it is one of the safest and most stable countries in the world. Switzerland is famous for its high-quality education and high-level technological development and is very competitive in biomedicine, chemical engineering, electronics and metal industries in the international market. As a small country with poor resources, the Swiss have learnt to drive their economic and social development through education, R&D and innovation a very long time ago. Some renowned enterprises, including Nestle, Novartis and Roche, are all based in Switzerland. Meanwhile, a lot of creative small-sized and medium-sized enterprises based in Switzerland are dedicated to supporting the export-orientation economy in Switzerland.
Switzerland has the strongest economic strength and plentiful innovation energy. Its patent applications, publication of essay, frequencies of quotation and private enterprises’ innovation performance are remarkable all over the world. According to the Global Competitiveness Report released by the World Economic Forum (WEF), Switzerland has ranked first among the most competitive countries in the world for four years consecutively since 2009[2]. Meanwhile, according to the Global Innovation Index (GII) released by INSEAD and the World Intellectual Property Organization (WIPO) jointly, Switzerland has also ranked first in 2011 and 2012 consecutively[3]. Obviously, Switzerland has led the other countries in the world in innovation development and economic strength. Therefore, when studying the R&D incentives and boosting the industrial innovation, we might benefit from the experience of Switzerland to help boost the relevant mechanism in Taiwan.
Taiwan’s government organization reform has been launched officially and boosted step by step since 2012. In the future, the National Science Council will be reformed into the “Ministry of Science and Technology”, and the Ministry of Economic Affairs into the “Ministry of Economy and Energy”, and the Department of Industrial Development into the “Department of Industry and Technology”. Therefore, Taiwan’s technology administrative system will be changed materially. Under the new government organizational framework, how Taiwan’s technology R&D and industrial innovation system divide work and coordinate operations to boost the continuous economic growth in Taiwan will be the first priority without doubt. Support of innovation policies is critical to promotion of continuous economic growth. The Swiss Government supports technological research and innovation via various organizations and institutions effectively. In recent years, it has achieved outstanding performance in economy, education and innovation. Therefore, we herein study the functions and orientation of the competent authorities dedicated to boosting research and innovation in Switzerland, and observe its policies and legal system applied to boost the national R&D in order to provide the reference for the functions and orientation of the competent authorities dedicated to boosting R&D and industrial innovation in Taiwan.
II. Overview of Swiss Federal Technology Laws and Technology Administrative System
Swiss national administrative organization is subject to the council system. The Swiss Federal Council is the national supreme administrative authority, consisting of 7 members elected from the Federal Assembly and dedicated to governing a Federal Government department respectively. Switzerland is a federal country consisting of various cantons that have their own constitutions, councils and governments, respectively, entitled to a high degree of independence.
Article 64 of the Swiss Federal Constitution[4] requires that the federal government support research and innovation. The “Research and Innovation Promotion Act” (RIPA)[5] is dedicated to fulfilling the requirements provided in Article 64 of the Constitution. Article 1 of the RIPA[6] expressly states that the Act is enacted for the following three purposes: 1. Promoting the scientific research and science-based innovation and supporting evaluation, promotion and utilization of research results; 2. Overseeing the cooperation between research institutions, and intervening when necessary; 3. Ensuring that the government funding in research and innovation is utilized effectively. Article 4 of the RIPA provides that the Act shall apply to the research institutions dedicated to innovation R&D and higher education institutions which accept the government funding, and may serve to be the merit for establishment of various institutions dedicated to boosting scientific research, e.g., the National Science Foundation and Commission of Technology & Innovation (CTI). Meanwhile, the Act also provides detailed requirements about the method, mode and restriction of the government funding.
According to the RIPA amended in 2011, the Swiss Federal Government’s responsibility for promoting innovation policies has been extended from “promotion of technology R&D” to “unification of education, research and innovation management”, making the Swiss national industrial innovation framework more well-founded and consistent[8] . Therefore, upon the government organization reform of Switzerland in 2013, most of the competent authorities dedicated to technology in Swiss have been consolidated into the Federal Department of Economic Affairs, Education and Research.
Under the framework, the Swiss Federal Government assigned higher education, job training, basic scientific research and innovation to the State Secretariat for Education, Research and Innovation (SERI), while the Commission of Technology & Innovation (CTI) was responsible for boosting the R&D of application scientific technology and industrial technology and cooperation between the industries and academy. The two authorities are directly subordinate to the Federal Department of Economic Affairs, Education and Research (EAER). The Swiss Science and Technology Council (SSTC), subordinate to the SERI is an advisory entity dedicated to Swiss technology policies and responsible for providing the Swiss Federal Government and canton governments with the advice and suggestion on scientific, education and technology innovation policies. The Swiss National Science Foundation (SNSF) is an entity dedicated to boosting the basic scientific R&D, known as the two major funding entities together with CTI for Swiss technology R&D. The organizations, duties, functions and operations of certain important entities in the Swiss innovation system are introduced as following.
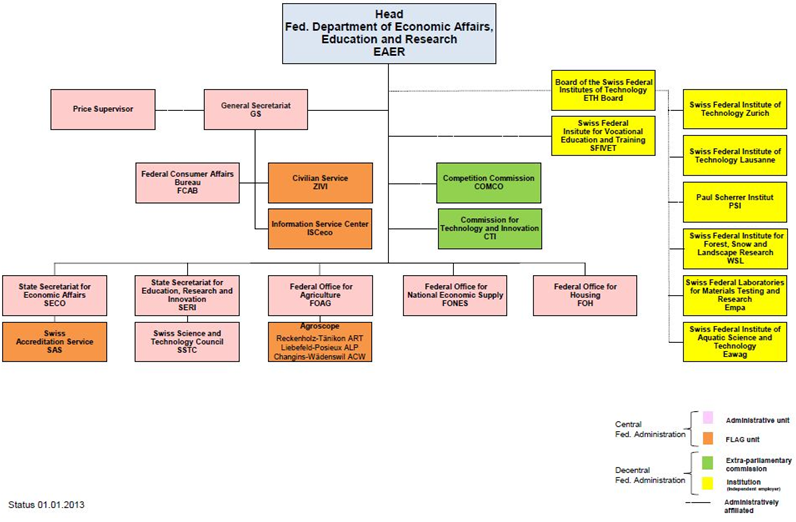
Date source: Swiss Federal Department of Economic Affairs, Education and Research official website
Fig. 1 Swiss Innovation Framework Dedicated to Boosting Industries-Swiss Federal Economic, Education and Research Organizational Chart
1. State Secretariat of Education, Research and Innovation (SERI)
SERI is subordinate to the Department of Economic Affairs, Education and Research, and is a department of the Swiss Federal Government dedicated to managing research and innovation. Upon enforcement of the new governmental organization act as of January 1, 2013, SERI was established after the merger of the State Secretariat for Education and Research, initially subordinate to Ministry of Interior, and the Federal Office for Professional Education and Technology (OEPT), initially subordinated to Ministry of Economic Affairs. For the time being, it governs the education, research and innovation (ERI). The transformation not only integrated the management of Swiss innovation system but also unified the orientations toward which the research and innovation policy should be boosted.
SERI’s core missions include “enactment of national technology policies”, “coordination of research activities conducted by higher education institutions, ETH, and other entities of the Federal Government in charge of various areas as energy, environment, traffic and health, and integration of research activities conducted by various government entities and allocation of education, research and innovation resources. Its functions also extend to funding the Swiss National Science Foundation (SNSF) to enable SNSF to subsidize the basic scientific research. Meanwhile, the international cooperation projects for promotion of or participation in research & innovation activities are also handled by SERI to ensure that Switzerland maintains its innovation strength in Europe and the world.
The Swiss Science and Technology Council (SSTC) is subordinate to SERI, and also the advisory unit dedicated to Swiss technology policies, according to Article 5a of RIPA[9]. The SSTC is responsible for providing the Swiss Federal Government and canton governments with advice and suggestion about science, education and innovation policies. It consists of the members elected from the Swiss Federal Council, and a chairman is elected among the members.
2. Swiss National Science Foundation (SNSF)
The Swiss National Science Foundation (SNSF) is one of the most important institutions dedicated to funding research, responsible for promoting the academic research related to basic science. It supports about 8,500 scientists each year. Its core missions cover funding as incentives for basic scientific research. It grants more than CHF70 million each year. Nevertheless, the application science R&D, in principle, does not fall in the scope of funding by the SNSF. The Foundation allocates the public research fund under the competitive funding system and thereby maintains its irreplaceable identity, contributing to continuous output of high quality in Switzerland.
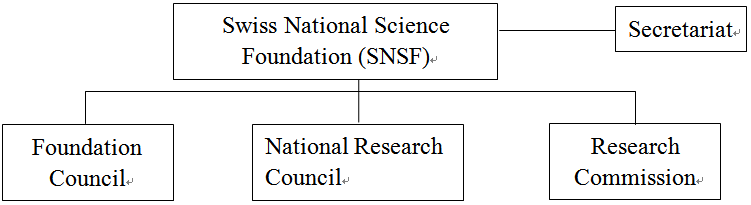
With the support from the Swiss Federal Government, the SNSF was established in 1952. In order to ensure independence of research, it was planned as a private institution when it was established[10]. Though the funding is provided by SERI, the SNSF still has a high degree of independence when performing its functions. The R&D funding granted by the SNSF may be categorized into the funding to free basic research, specific theme-oriented research, and international cooperative technology R&D, and the free basic research is granted the largest funding. The SNSF consists of Foundation Council, National Research Council and Research Commission[11].
Data source: prepared by the Study
Fig. 2 Swiss National Science Foundation Organizational Chart(1) Foundation CouncilThe Foundation Council is the supreme body of the SNSF[12], which is primarily responsible for making important decisions, deciding the role to be played by the SNSF in the Swiss research system, and ensuring SNSF’s compliance with the purpose for which it was founded. The Foundation Council consists of the members elected from the representatives from important research institutions, universities and industries in Swiss, as well as the government representatives nominated by the Swiss Federal Council. According to the articles of association of the SNSF[13], each member’s term of office should be 4 years, and the members shall be no more than 50 persons. The Foundation Council also governs the Executive Committee of the Foundation Council consisting of 15 Foundation members. The Committee carries out the mission including selection of National Research Council members and review of the Foundation budget.
(2) National Research Council
The National Research Council is responsible for reviewing the applications for funding and deciding whether the funding should be granted. It consists of no more than 100 members, mostly researchers in universities and categorized, in four groups by major[14], namely, 1. Humanities and Social Sciences; 2. Math, Natural Science and Engineering; 3. Biology and Medical Science; and 4. National Research Programs (NRPs)and National Centers of Competence in Research (NCCRs). The NRPs and NCCRs are both limited to specific theme-oriented research plans. The funding will continue for 4~5years, amounting to CHF5 million~CHF20 million[15]. The specific theme-oriented research is applicable to non-academic entities, aiming at knowledge and technology transfer, and promotion and application of research results. The four groups evaluate and review the applications and authorize the funding amount.
Meanwhile, the representative members from each group form the Presiding Board dedicated to supervising and coordinating the operations of the National Research Council, and advising the Foundation Council about scientific policies, reviewing defined funding policies, funding model and funding plan, and allocating funding by major.
(3) Research Commissions
Research Commissions are established in various higher education research institutions. They serve as the contact bridge between higher education academic institutions and the SNSF. The research commission of a university is responsible for evaluating the application submitted by any researcher in the university in terms of the school conditions, e.g., the school’s basic research facilities and human resource policies, and providing advice in the process of application. Meanwhile, in order to encourage young scholars to attend research activities, the research committee may grant scholarships to PhD students and post-doctor research[16].
~to be continued~
[1] SWISS FEDERAL STATISTICS OFFICE, Switzerland's population 2011 (2012), http://www.bfs.admin.ch/bfs/portal/en/index/news/publikationen.Document.163772.pdf (last visited Jun. 1, 2013).
[2] WORLD ECONOMIC FORUM [WEF], The Global Competiveness Report 2012-2013 (2012), http://www3.weforum.org/docs/WEF_GlobalCompetitivenessReport_2012-13.pdf (last visited Jun. 1, 2013); WEF, The Global Competiveness Report 2011-2012 (2011), http://www3.weforum.org/docs/WEF_GCR_Report_2011-12.pdf (last visited Jun. 1, 2013); WEF, The Global Competiveness Report 2010-2011 (2010), http://www3.weforum.org/docs/WEF_GlobalCompetitivenessReport_2010-11.pdf (last visited Jun. 1, 2013); WEF, The Global Competiveness Report 2009-2010 (2009),. http://www3.weforum.org/docs/WEF_GlobalCompetitivenessReport_2009-10.pdf (last visited Jun. 1, 2013).
[3] INSEAD, The Global Innovation Index 2012 Report (2012), http://www.globalinnovationindex.org/gii/GII%202012%20Report.pdf (last visited Jun. 1, 2013); INSEAD, The Global Innovation Index 2011 Report (2011), http://www.wipo.int/freepublications/en/economics/gii/gii_2011.pdf (last visited Jun. 1, 2013).
[4] SR 101 Art. 64: “Der Bund fördert die wissenschaftliche Forschung und die Innovation.”
[5] Forschungs- und Innovationsförderungsgesetz, vom 7. Oktober 1983 (Stand am 1. Januar 2013). For the full text, please see www.admin.ch/ch/d/sr/4/420.1.de.pdf (last visited Jun. 3, 2013).
[6] Id.
[7] Id.
[8] CTI, CTI Multi-year Program 2013-2016 7(2012), available at http://www.kti.admin.ch/?lang=en&download=NHzLpZeg7t,lnp6I0NTU042l2Z6ln1ad1IZn4Z2qZpnO2Yuq2Z6gpJCDeYR,hGym162epYbg2c_JjKbNoKSn6A-- (last visited Jun. 3, 2013).
[9] Supra note 5.
[10] Swiss National Science Foundation, http://www.snf.ch/E/about-us/organisation/Pages/default.aspx (last visited Jun. 3, 2013).
[11] Id.
[12] Foundation Council, Swiss National Science Foundation, http://www.snf.ch/E/about-us/organisation/Pages/foundationcouncil.aspx (last visited Jun. 3, 2013).
[13] See Statutes of Swiss National Science Foundation Art.8 & Art. 9, available at http://www.snf.ch/SiteCollectionDocuments/statuten_08_e.pdf (last visited Jun. 3, 2013).
[14] National Research Council, Swiss National Science Foundation, http://www.snf.ch/E/about-us/organisation/researchcouncil/Pages/default.aspx (last visted Jun.3, 2013).
[15] Theres Paulsen, VISION RD4SD Country Case Study Switzerland (2011), http://www.visionrd4sd.eu/documents/doc_download/109-case-study-switzerland (last visited Jun.6, 2013).
[16] Research Commissions, Swiss National Science Foundation, http://www.snf.ch/E/about-us/organisation/Pages/researchcommissions.aspx (last visted Jun. 6, 2013).

Executive Yuan roll-out The Policy of “The Free Economic Pilot Zones” 1.Executive Yuan approved a Bill titled “The Free Economic Pilot Zones Special Act” The “Free Economic Demonstration Zones” (hereinafter as FEDZs) is a critical part to improve the liberalization and internationalization of the economy of Republic of China (R.O.C). By deregulation, FEDZs was conceived as trial zones. Once the results of the program were promising, it would be expanded to the entire country. In order to engage in the regional economic and trade integration, the Executive Yuan approved a Bill titled “The Free Economic Pilot Zones Special Act” (hereinafter as Bill) on April 26th, 2013. On Mar 6th, 2014, the Joint Economic, Internal Administration , and Finance Committee of the Legislation Yuan (the Congress) discussed the Bill for reports and questions. By the end of the March, 2014, the Congress will hold five public hearings. Not until the discussion of the Bill item by item and the passage in the Congress, the second stage of the FEDZ program would not be initiated. There are five main points, including the treatments on foreigners and people from mainland China, tax incentives for Taiwanese businessman, foreign professionals and foreign companies, regulations on untaxed goods and labor, regulations on industrial development, such as the agriculture and the medical, and certain new items on education and professional services. For the reason that the government considered the need of human resources to sustain the operation of the industries, the Executive Yuan is trying to promote innovative education in FEPZs. Since the education requirements for both of public and private universities are unified in local, colleges and universities were restrained and missed some great opportunities to discover their own niches in education. Hence, innovative education in FEPZs is trying to help higher education system to introduce foreign education resources and foresight concepts, and to attract more international students. The innovative educational projects within FEPZs will also facilitate the cooperations among domestic and foreign universities, and set up experimental branch campuses, colleges, degree programs or professional courses. Besides, the financial service sector is also included. Since FEDZs is an important pusher for R.O.C to move forward in regional economic integration, accordingly, the most significant liberate item for the financial industry in the FEPZs is to allow offshore banking units and offshore security units to provide financial products and service (e.g. OSU and OBU). Meanwhile, the financial industry is predicted to receive an NTD$140 billion or more in revenues over the next five year. In summary, FEPZs is regarded as a engine propelling liberalization and internationalization. To gain the international competitiveness, the government will continue to promote policies and measures. By establishing the free economic demonstration zone, it is expected to create innovative effects into the education system and to create more job opportunities. 2.Legislation Yuan has reviewd “The Free Ecomonic Pilot Zones Special Act” The Republic of China (R.O.C) have been carried out “free economic” recent years, by promoting “Free Economic Pilot Zone” (hereinafter as FEPZs) to encourage every industrial and foreign investment. Besides, FEPZs will not only keep talents and technologies in R.O.C but also liberalize and internationalize our economic. The Executive Yuan had approved a Bill titled “The Free Economic Pilot Zones Special Act” (hereinafter as the Bill) on Dec. 26th, 2013. At the end of May, the Joint Economic, Internal Administration, and Finance Committee of the Legislation Yuan (the Congress) have taken five public hearings for the Bill, and amended the Bill according to the advices proposed by specialists. Not until the deliberation of the Bill item by item and its passage in the Congress, the second stage of the FEDZ program would not be initiated. There are five main points, including the treatments on foreigners, tax incentives for R.O.C businessman, foreign professionals and foreign companies, regulations on untaxed goods and labor, regulations on industrial development, such as the agriculture and the medical service, and certain new items on education and professional services. The government considers that there have to be enough human resource to sustain the opened industries, so Executive Yuan is trying to promote innovative education in FEPZs. The core concept of FEPZs is foresight, liberalization and internationalization, the premier said, and the higher education systems belong to high-end service and have much more marketability and variability compared to other education systems. Through innovative and efficient way to manage the school could let University being much more liberalized. Furthermore, the higher education systems in R.O.C. have to connect with international education to avoid being marginalized. Our first stage of education innovation will promote to set up “degree programs” and “professional courses”. The first phase for the Ministry of Education is going to found “degree programs” or “professional courses” through collaboration way. The Ministry of Education will also draw up related regulations or guidance on standards for school cooperation, co-regulation, setup conditions, supervision, enrolling new student, and recruiting staff.? Once the Bills pass, The Ministry of Education plans to establish “branch school” and “independence campus” helping R.O.C. higher education goes internationalized. On the other hand, Our medical service also has strong international competitiveness. R.O.C is engage in developing international medical and health industry. The premier said, the Ministry of Health and Welfare have proposed some measures, such as limitation to the number of medical centre, medical personnel working hours, and NHI is not allow to use in the zones. The premier added, on the extemporaneous sittings, “The Free Economic Pilot Zones Special Act” will be the priority bills and be deliberated in the end of June By establishing the free economic demonstration zone, it is expected to propel R.O.C take part in Trans-Pacific Partnership (TPP) and the Regional Comprehensive Economic Partnership (RCEP). 3.Executive Yuan’s rapid roll-out of “The Free Economic Pilot Zones”, and has published a report concerning the legal and economic implications of its the Bill The “Free Economic Pilot Zones” (hereinafter as FEPZs) plays a pivotal role in promoting market liberalization, especially at an international level. Premier of the Executive Yuan, Mr. Jiang Yi-Hua has stated that the “market economy” and “innovation economy” allows for tremendous economic prosperity to be embraced by the Republic of China (hereinafter as R.O.C). The seizing of such opportunity has been the goal of government efforts, which can be attested by the recent proposal of the “The Free Economic Pilot Zones Special Act” (hereinafter as the Bill), currently undergoing review and consultation proceedings. The Premier further stressed that the national economy should not be left excluded from international commerce, on the other hand, it is imperative that closer economic bonds with other nations are forged, therefore allowing itself open up to wider scope of opportunities for growth. The key in rendering this possible is through the enactment of laws. At a time, when Trans-Pacific nations, including the United States of America, Japan and countries from Southeast Asia, are working towards regional economic cooperation, if R.O.C. is to be left out, it is feared that its position in the global market would further be marginalized. The core innovative strengths of the FEPZs include “Smart Logistics”, “International healthcare services”, “Value added agriculture”, “Financial Services”, “Education Innovation”, all of which are implemented by employing R.O.C.’s finest workforce, knowledge, information and communications technology (ICT), geographical position and cross-strait relationship advantages, leading way for an advantageous basis for pioneering economic development. The first stage of development will be based on 6 locations proximal to the sea (including Keelung Port, Taipei Port, Kaohsiung Port, Suao Harbor, Anping Port, Taichung Port) and Taoyuan Aerotropolis and Pingtung Agricultural Biotech Park. The second stage of development would only commence after the Bill have been approved by the legislative Yuan, which would attract much capital investment, hence boosting high employment rates. Presently, besides the aforementioned regions opened up for the FEPZs, other cities and industrial sites (including those from offshore islands), are striving to gain membership of the FEPZs, or applying for empirical research of the FEPZs. The Executive Yuan has published a report concerning the legal and economic implications of its the Bill on May 2014. The report largely consists of assessments made by varying governing bodies, such as Ministry of Home Affairs, Financial Supervisory Commission etc., on the implications of the draft concerning real estate, employment, fiscal income, logistics, conditions for medical care, agriculture, higher education, social environment and social wealth redistribution etc. Furthermore, international attention has been closely centered on the progress of FEPZs. During the “The third review of the trade policies and practices of Chinese Taipei” after R.O.C accession to the World Trade Organization (WTO) held on the 17th of September 2014 in Geneva, each member state has demonstrated expectations arising out of the direction and planning undertaken for the FEPZs. National economic and international commercial reforms are under way and have seen much progress in further promoting the overall strength of the economic system, in an effort to respond to the rapid global political and economic developments, for example, through the signing of Economic Cooperation Framework Agreement (ECFA), and the implementation of FEPZs policies. In the future, it will be expected that R.O.C. will strive for a more integral international commercial system, allowing much capital investment inflows as well as the cultivating of high-caliber human resources. To promote more liberal and internationalized development of Taiwan economy, government of Republic of China (R.O.C) approved the “Free Economic Pilot Zone (FEPZ) Plan,” which the Bill is currently censored in Legislation Yuan and the measures would be implemented in two phases. The first phase of FEPZs would be initiated within six free trade ports, Taoyuan airport free trade zone, and Pingtung Agricultural Biotechnology Park; other industries that match up with the idea of liberalization, internationalization and foresight can all be incorporated into FEPZ through continuing examination under Execution Yuan. After this special legislation is passed, the set-ups of demonstration zones can be applied by authorities either of central or of local government and the related promotion works of the second phase will be unfolded immediately. Heading to the target of becoming Kin-Xiao (Kinmen and Xiaomen) Free Trade Zone, Kinmen government planned to apply to be one of the FEPZs and thus cooperated with Taiwan Institute of Economic Research (TIER) on December 11, for a commissioned research (which was later released on the conference of accelerating Kin-Xia FTZ on December 19) on evaluating if Kinmen is qualified for an application of FEPZs. Kinmen’s critical location and the featured industries have composed a perfect environment complying with the ideas such as value-added agriculture, international healthcare and innovative education for FEPZ. For instance, the white liquor industry in Kinmen represents the international management and promotion of agricultural products, and is the best example for value-added agriculture. “Long-term Healthcare Village in Kinmen,” which is currently developing in Kinmen, would also be a drive for international healthcare industry. Based on the Taiwan-featured culture, “International Education City” could be developed with a liberal and innovative atmosphere, which would attract famous schools in world to set up their branch school in Kinmen. Above all, Kinmen County vice Mayor, Wu Yo-Chin, indicated that Kinmen would be the first choice for FEPZ and would hold the key to open a new gate for the Cross-Strait. The vice Mayor emphasized that Kinmen government has well budgeting and financial management, which needn’t the extra aids from central government, yet Kinmen was excluded in the first phase of FEPZs. Although Kinmen would apply to be a FEPZ in the second phase after the special legislation passed, Kinmen still strived for taking part in the first phase of FEPZs due to the uncertain schedule for implementation of regulations on FEPZs. National Development Council (NDC), however, gave an opinion on issue of Kinmen applying to be in the first phase of FEPZs, which declared again the original plan for the first phase only included six free trade ports, Taoyuan airport free trade zone, and Pingtung Agricultural Biotechnology Park. NDC also suggested Kinmen could still follow after the first phase and apply to be a FEPZ in the second phase.
The Tax Benefit of “Act for Establishment and Administration of Science Parks” and the Relational Norms for InnovationThe Tax Benefit of “Act for Establishment and Administration of Science Parks” and the Relational Norms for Innovation “Act for Establishment and Administration of Science Parks” was promulgated in 1979, and was amended entirely in May 15, 2018, announced in June 6. The title was revised from “Act for Establishment and Administration of Science ‘Industrial’ Parks” to “Act for Establishment and Administration of Science Parks” (it would be called “the Act” in this article). It was a significant transition from traditional manufacture into technological innovation. For encouraging different innovative technology enter into the science park, there is tax benefit in the Act. When the park enterprises import machines, equipment, material and so on from foreign country, the import duties, commodity tax, and business tax shall be exempted; moreover, when the park enterprises export products and services, it will have given favorable business and commodity tax free.[1] Furthermore, the park bureaus also exempt collection of land rent.[2] If they have approval for importing or exporting products, they do not need to apply for permission.[3] In the sub-law, there is also regulations of bonding operation.[4] To sum up, for applying the benefit of the act, enterprises approved for establishment in science parks still require to manufacture products. Such regulations are confined to industrial industry. Innovative companies dedicate in software, big data, or customer service, rarely gain benefits from taxation. In other norms,[5] there are also tax deduction or exemption for developing innovative industries. Based on promoting innovation, the enterprises following the laws of environmental protection, laborers’ safety, food safety and sanitation,[6] or investing in brand-new smart machines for their own utilize,[7] or licensing their intellectual property rights,[8] can deduct from its taxable income. In addition, the research creators from academic or research institutions,[9] or employee,[10] can declare deferral of the income tax payable for the shares distributed. In order to assist new invested innovative enterprises,[11] there are also relational benefit of tax. For upgrading the biotech and new pharmaceuticals enterprises, when they invest in human resource training, research and development, they can have deductible corporate income tax payable.[12] There is also tax favored benefits for small and medium enterprises in using of land, experiment of research, technology stocks, retaining of surplus, and additional employees hiring.[13] The present norms of tax are not only limiting in space or products but also encouraging in “research”. In other word, in each steps of the research of innovation, the enterprises still need to manufacture products from their own technology, fund and human resources. If the government could encourage open innovation with favored taxation, it would strengthen the capability of research and development for innovative enterprises. Supporting the innovation by taxation, the government can achieve the goal of scientific development more quickly and encourage them accepting guidance. “New York State Business Incubator and Innovation Hot Spot Support Act” can be an example, [14]the innovative enterprises accepting the guidance from incubators will have the benefit of tax on “personal income”, “sales and use” and “corporation franchise”. Moreover, focusing on key industries and exemplary cases, there are also the norms of tax exemption and tax abatement in China for promoting the development of technology.[15]The benefit of tax is not only in research but also in “the process of research”. To sum up, the government of Taiwan provides the benefit of tax for advancing the competition of outcomes in market, and for propelling the development of innovation. In order to accelerate the efficiency of scientific research, the government could draw lessons from America and China for enacting the norms about the benefit of tax and the constitution of guidance. [1] The Act §23. [2] Id. §24. [3] Id. §25. [4] Regulations Governing the Bonding Operations in Science Parks. [5] Such as Act for Development of Small and Medium Enterprises, Statute for Industrial Innovation, Act for the Development of Biotech and New Pharmaceuticals Industry. [6] Statute for Industrial Innovation §10. [7] Id. §10-1. [8] Id. §12-1. [9] Id. §12-2. [10] Id. §19-1. [11] Id. §23-1, §23-2, §23-3. [12] Act for the Development of Biotech and New Pharmaceuticals Industry §5, §6, §7. [13] Act for Development of Small and Medium Enterprises Chapter 4: §33 to §36-3. [14] New York State Department of Taxation and Finance Taxpayer Guidance Division, New York State Business Incubator and Innovation Hot Spot Support Act, Technical Memorandum TSB-M-14(1)C, (1)I, (2)S, at 1-6 (March 7, 2014), URL:http://www.wnyincubators.com/content/Innovation%20Hot%20Spot%20Technical%20Memorandum.pdf (last visited:December 18, 2019). [15] Enterprise Income Tax Law of the People’s Republic of China Chapter 4 “Preferential Tax Treatments”: §25 to §36 (2008 revised).
The Study of Estonian Human Genes DatabaseI. Introduction The human genes database or human genome project, the product under the policy of biotechnology no matter in a developed or developing country, has been paid more attention by a government and an ordinary people gradually. The construction of human genes database or human genome project, which is not only related to a country’s innovation on biotechnology, but also concerns the promotion of a country’s medical quality, the construction of medical care system, and the advantages brought by the usage of bio-information stored in human genes database or from human genome project. However, even though every country has a high interest in setting up human genes database or performing human genome project, the issues concerning the purposes of related biotechnology policies, the distribution of advantages and risks and the management of bio-information, since each country has different recognition upon human genes database or human genome project and has varied standards of protecting human basic rights, there would be a totally difference upon planning biotechnology policies or forming the related systems. Right now, the countries that vigorously discuss human genes database or practice human genome project include England, Iceland, Norway, Sweden, Latvia and Estonia. Estonia, which is the country around the Baltic Sea, has planned to set up its own human genes database in order to draw attention from other advanced countries, to attract intelligent international researchers or research groups, and to be in the lead in the area of biotechnology. To sum up, the purpose of constructing Estonian human genes database was to collect the genes and health information of nearly 70% Estonia’s population and to encourage bio-research and promote medical quality. II. The Origin of Estonian Human Genes Database The construction of Estonian human genes database started from Estonian Genome Project (EGP). This project was advocated by the professor of biotechnology Andres Metspalu at Tartu University in Estonia, and he proposed the idea of setting up Estonian human genes database in 1999. The purposes of EGP not only tried to make the economy of Estonia shift from low-cost manufacturing and heavy industry to an advanced technological economy, but also attempted to draw other countries’ attention and to increase the opportunity of making international bio-researches, and then promoted the development of biotechnology and assisted in building the system of medical care in Estonia. EGP started from the agreement made between Estonian government and Eesti Geenikeskus (Estonian Genome Foundation) in March, 1999. Estonian Genome Foundation was a non-profit organization formed by Estonian scientists, doctors and politicians, and its original purposes were to support genes researches, assist in proceeding any project of biotechnology and to set up EGP. The original goals of constructing EGP were “(a) reaching a new level in health care, reduction of costs, and more effective health care, (b) improving knowledge of individuals, genotype-based risk assessment and preventive medicine, and helping the next generation, (c) increasing competitiveness of Estonia – developing infrastructure, investments into high-technology, well-paid jobs, and science intensive products and services, (d) [constructing] better management of health databases (phenotype/genotype database), (e) … [supporting]… economic development through improving gene technology that opens cooperation possibilities and creates synergy between different fields (e.g., gene technology, IT, agriculture, health care)”1. III. The Way of Constructing Estonian Human Genes Database In order to ensure that Estonian human genes database could be operated properly and reasonably in the perspectives of law, ethics and society in Estonia, the Estonian parliament followed the step of Iceland to enact “Human Genes Research Act” (HGRA) via a special legislative process to regulate its human genes database in 2000. HGRA not only authorizes the chief processor to manage Estonian human genes database, but also regulates the issues with regard to the procedure of donation, the maintenance and building of human genes database, the organization of making researches, the confidential identity of donator or patient, the discrimination of genes, and so on. Since the construction of Estonian human genes database might bring the conflicts of different points of view upon the database in Estonia, in order to “avoid fragmentation of societal solidarity and ensure public acceptability and respectability”2 , HGRA adopted international standards regulating a genes research to be a norm of maintaining and building the database. Those standards include UNESCO Universal Declaration on the Human Genome and Human Rights (1997) and the Council of Europe’s Convention on Human Rights and Biomedicine (1997). The purpose of enacting HGRA is mainly to encourage and promote genes researches in Estonia via building Estonian human genes database. By means of utilizing the bio-information stored in the database, it can generate “more exact and efficient drug development, new diagnostic tests, improved individualized treatment and determination of risks of the development of a disease in the future”3 . In order to achieve the above objectives, HGRA primarily puts emphasis on several aspects. Those aspects include providing stronger protection on confidential identity of donators or patients, caring for their privacy, ensuring their autonomy to make donations, and avoiding any possibility that discrimination may happen because of the disclosure of donators’ or patients’ genes information. 1.HERBERT GOTTWEIS & ALAN PETERSEN, BIOBANKS – GOVERNANCE IN COMPARATIVE PERSPECTIVE 59 (2008). 2.Andres Rannamae, Populations and Genetics – Legal and Socio-Ethical Perspectives, in Estonian Genome Porject – Large Scale Health Status Description and DNA Collection 18, 21 (Bartha Maria Knoppers et al. eds., 2003. 3.REMIGIUS N. NWABUEZE, BIOTECHNOLOGY AND THE CHALLENGE OF PROPERTY – PROPERTY RIGHTS IN DEAD BODIES, BODY PARTS, AND GENETIC INFORMATION, 163 (2007).
Introduction to Tax Incentive Regime for SMEsIntroduction to Tax Incentive Regime for SMEs I. Introduction The developments of SMEs (small-and-medium enterprises) plays an important pillar of development of industries and creation of jobs in Taiwan. In 2017, the total number of SMEs in Taiwan was 1,437,616. They offer 8,904,000 jobs, accounting for 78.44% of the workforce[1]. However, SMEs have difficulties in entering international supply chains because of their weakness in finance. Therefore, how to enhance the global competitiveness of SMEs is an important issue for the concerned authority. Chapter 4 of the Act for Development of Small and Medium Enterprises prescribes the tax incentive regime based on the financial capability of SMEs and characteristics of industries in order to facilitate the development of SMEs, especially the globalization of SMEs. This paper will review the importance of tax incentives to SMEs and introduces the tax incentive regime under the Act for Development of Small and Medium Enterprises In order to help SMES have an understanding of such regime. II. SME Tax Incentives Scheme As the gatekeeper of the market, the government may intervene the market with various policies or tools to reallocate and improve the soundness of the market environment when the market competitions is impaired due to information asymmetry or externalities. At this juncture, preferential tax rates or tax deductions can be offered to specific taxpayers through legal institution. This allows these taxpayers to retain higher post-tax earnings so that they are incentified to invest more resources in the legally defined economic activities. Tax incentives targeting at risky or spillover investments to create benefits to specific economic activities will help the development of industries and markets. Whilst Article 10 of the Statute for Industrial Innovation has provided tax cuts for R&D expenditures, these incentives are not focus on SMEs and hence not supportive to their research and innovations. This was the reason for the 2016 amendment of the Act for Development of Small and Medium Enterprises added Article 35 to offer tax incentives in order to encourage R&D and innovative efforts and Article 35-1 to activate intellectual properties via licensing. These articles aim to accelerate the momentum of innovations and transformations which promoting investments for SMEs. OthersTo assist SMEs to cope with change of the business environment, the Article 36-2 added the tax incentives for salary or headcount increases, to contribute to the sustainability of SMEs and stabilize the labour market and industrial structures. Following is an explanation of the applicability of these schemes and the requirements to qualify such incentives. III. Tax Incentives to Promote Investments (I) Tax deductions for R&D expenditures Governments around the world seek to encourage corporate R&D activities, that Tax incentives are put in place to reduce R&D costs and foster a healthy environment of investment for more R&D initiatives. Neighboring countries such as Japan, Korea and Singapore are frequently practicing belowing tax burdens to encourage R&D efforts. Article 35 of the Act for Development of Small and Medium Enterprises in Taiwan allows accelerated depreciation and offers tax cuts[2] to stimulate R&D and innovations and create an investment friendly environment for SMEs. 1. Taxpaying Entities and Requirements (1) Qualifications for SMEs Article 35 of the Act is applicable to qualified SMEs and individual taxpayers, which are (1) from manufacturing, construction & engineering, mining and quarrying industries, with paid-in capital below or equal to NT$80 million or with the number of full-time employees less than 200 people; (2) from other industries with the sales of the previous year below or equal to NT$100 million or with the number of full-time employees less than 100 people. Thus, the qualifications of Small and Medium Enterprises are based on either paid-in capital/sales or number of employees under the Act[3].Meanwhile, SMEs may not have an independent R&D department due to the limit of size or operating cost.Therefore, if the taxpayers hiring full-time R&D personnel that can provide records of job descriptions and work logs to R&D activities, the SMEs can access the tax incentives provided that the R&D functions. The recognized by government agencies is increasingly flexibility for SMEs seeking policy support. 2. Taxpayers and requirements (1) A certain degree of innovativeness As the tax incentive regime strives to promote innovations, the R&D expenses should be used to fund innovative developments. According to the official letters from the Small and Medium Enterprise Administration, Ministry of Economic Affairs, there is no high bar as forward-looking, risky and innovative as usually” required for other incentives previously, which is considering the size of SMEs and their industry characteristics. The “certain degree” of innovativeness shall be based on industry environments and SME businesses as determined by competent authorities in a flexible manner. (2) Flexibility in the utilization of business income tax reductions To encourage regular R&D activities, The case that SMEs may not have R&D undertakings each year due to funding constraints, or start-up company may have incurred R&D expenditures but are not yet profitable and hence have no tax liabilities during the year, Corporate taxpayers were able to choose beside deduct the payable taxes during a single year, and reduce the payable taxes during the current year over three years starting from the year when tax incentives are applicable. 3. Tax incentive effects As previously mentioned, Article 35 of the Act for Development of Small and Medium Enterprises accommodates the characteristics of SMEs by allowing reductions of corporate business taxes for up to 15% R&D expenditures during the current year, or spreading the tax reductions by spreading up to 10% of the R&D expenditures over three years from the first year when the incentives are applicable. It is worth noting that the tax deductions shall not exceed 30% of the payable business income taxes during a single year. If the instruments and equipment for R&D, experiments or quality inspections have a lifetime over two years or longer, it is possible to accelerate the depreciation within half of the years of service prescribed by the income tax codes for fixed assets. However, the final year less than 12 months over the shortened service years shall not be counted. Accelerated depreciation brings in tax benefits for fixed asset investments during the initial stage, that meets the requirements for new technologies and risk management by frontloading the equipment depreciation and creates a buffer for capital utilization. (II) Deferred taxations on licensing/capitalization of intellectual properties The deferral of tax payments under the Act for Development of Small and Medium Enterprises is meant to avoid any adverse effect on the application of technological R&Ds by SMEs. As the equity stakes via capitalization of intellectual properties by inventors or creators are not cashed out yet and the subsequent gains may not be at the same valuation as determined at the time of capitalization, the immediate taxation may hinder the willingness to transfer intellectual properties. Therefore, assisting SMEs to release intellectual properties with potential economic value, the licensing and capitalization of intellectual properties is strongly encouraged. The tax expenses shall be deferred within SME or an individual acquires stakes on a non-publicly-listed company by transferring their intellectual properties. This is to stimulate the applications and sharing of relevant manufacturing technologies. When an SME or an individual acquires stakes on a non-publicly-listed company by transferring their intellectual properties, their tax expenses shall be deferred. 1. Taxpayers and requirements (1) Qualifications for individuals or SMEs Article 35-1 of the Act for Development of Small and Medium Enterprises is applicable to SMEs and individual taxpayers. This is to foster the growth of SMEs and enhancement of industry competitiveness by encouraging R&D and innovations from individuals and start-ups. To promote the commercialize of intellectual properties in different ways, the Act for Development of Small and Medium Enterprises provides income tax incentives to individuals and SMEs transferring intellectual properties. The purpose is to encourage different paths to industry upgrades. (2) Ownership of intellectual properties To ensure that the proceeds of intellectual property is linked to the activity of intellectual properties which perform by individuals or SMEs. Only the owners of the intellectual properties capitalized and transferred can enjoy the tax benefits. Intellectual properties referred to in the Act for Development of Small and Medium Enterprises are the properties with value created with human activities and hence conferred with legal rights. These include but are not limited to copyrights, patent rights, trademarks, trade secrets, integrated circuit layouts, plant variety rights and any other intellectual properties protected by laws[4]. (3) Acquisition of stock options The abovementioned tax incentives are offered to the individuals or SMEs who transfer intellectual properties to non-listed companies in exchange of their new shares. The income taxes on the owners of intellectual properties are deferred until acquisition of shares. These shares are not registered with the book-entry system yet. Before the transferrers of intellectual properties dispose or offload these shares, immediate taxations will impose economic burdens and funding challenges given the unknown prices of the eventual cash-out. Therefore, this legislation is only applicable to taxpayers who obtain options for new shares. 2. Taxpayers and requirements (1) Transfer of intellectual properties According to Article 36 of the Copyright Act as interpreted by official letters issued by the Ministry of Finance, the transfer of intellectual properties is the conferring of intellectual properties to others, and the transferees access these intellectual properties within the scope of the transfer. In terms “transfer” of the first and second paragraphs of Article 36 does not include licensing[5], but such as granting, licensing and inheritance. (2) Timing of income tax payments In general, the particular time that calculation of taxes payable is based on when the taxpayers acquire the incomes, less relevant expenses or costs. The taxes payable timing should be depending on when the taxpayers obtain the newly issued shares by transferring intellectual properties. However, the levy of income taxes at the time of intellectual property transfers and new share acquisitions may cause a sudden jump in taxes payable in the progressive system and thus a burden on the economics of SMEs and individuals concerned. Thus, to avoid disruptions to company operations or personal finance planning, Article 36 makes the exception for the incomes earned by subscribing to new shares as a result of transferring intellectual properties. Such incomes are not subject to taxes during the year when the shares are acquired, in order to mitigate the tax barriers concerned. In sum, the taxes shall be paid when such shares are transferred, gifted or distributed. 3. Tax incentive effects Article 35-1 of the Act for Development of Small and Medium Enterprises provides tax incentives to stimulate the mobilization of intellectual properties by smoothing out the impact of income taxes payable. This is applicable to (1) SMEs who can postpone the business income taxes payable from the year when they acquire new shares of non-listed companies by transferring the intellectual properties they own; (2) individuals who can postpone the individual income taxes payable from the year when they acquire new shares of non-listed companies by transferring the intellectual properties they own. IV. Tax incentives aiming to improve the business environment (I) Tax reductions for wages to additional headcounts SMEs are vital to the Taiwan, making uo 90% of the companies accounting in Taiwan, who employ more than 6.5 million people or 72.8% of the total workforce. Any economic recession may make it difficult for SMEs to maintain their labor costs given their smaller funding size and external challenges. This will cause higher unemployment rates and hurt the economy, which may cause impairment of the capacity or create a labor gap for SMEs, eventually shrink the industry scale. To lower the burden of operational and investment costs and learn from the legislatives in Japan and the U.S.[6], tax incentives are put in place as a buffer for adverse effects of external environments. The first paragraph of Article 36-2 of the Act for Development of Small and Medium Enterprises provide tax incentives for employee salaries of new headcounts based on the assessment on the economy over a time period. This is intended to encourage domestic investments and avoid the pitfall of direct government subsidies distorting salary structures. It is hoped that investments from SMEs can stimulate the momentum of economic growth. 1. Taxpayers The tax incentives under Article 36-2 of the Act for Development of Small and Medium Enterprises aim to assist SMEs through difficult times in an economic downturn. The threshold of the period time is based on the unemployment rate has been below the economic indicator predetermined for six consecutive months, which calculated by the Directorate General of Budget, Accounting and Statistics, Executive Yuan. In number of the unemployment rate has been below the economic indicator predetermined for six consecutive months, it is deemed that the business environment is not friendly to SMEs. In this instance, the Regulations for the Tax Preferences Provided to Small and Medium-sized Enterprises on Additional Wage Payment will trigger the tax incentives. The abovementioned economic indicator shall be published by the competent authorities once every two years. Moreover, to qualify for the tax incentives for new employees, SMEs should investing new ventures or instill new capital by at least $500,000[7] or hiring workforce at least two full-time headcounts compared with the previous fiscal year, that constitute at the Article 36-2 of the Act for Development of Small and Medium Enterprises, which aims to encourage SMEs investments. 2. Taxpayers (1) Qualifications of additional headcounts As the dispatched human resource services typically meet temporary or short-term requirements and contractors do not enjoy employment security, this is not consistent with the spirit of the legislation to create jobs and reduce unemployment. Therefore, to avoid the one-time increase of headcounts from accessing the tax reductions during the year and the deterioration of labor relations in Taiwan. Tax incentive is not offered to the additional recruitment of part-time or contracted workers. Meanwhile, the tax incentives are only applicable to the additional employment of Taiwanese nationals, above or below 24 years old. A tax deduction of 50% based on annual wages is provided for the hiring of people below 24 years old. The extra tax deduction will stimulate young employment. (2) Definition of additional employment The number of additional headcounts is based on permanent hires and calculated as the difference between the average number of Taiwanese employees covered by labor insurance per month throughout a single fiscal year or before and after the incremental increase of workforce. The conversion of regular contracts to indefinite employment in writing or signing up for indefinite R&D headcounts under the military service scheme can also be deemed as additional employment. It is worth noting, however, the new headcounts resulted from M&A activities or transfer between affiliated companies are excluded in this legislation. (3) Calculation of wages Companies are also required to increase employment as well as the Comparable Wages. The comparable wages are estimated with the summation of 30% of the wages for the year before and after additional employment that based on the aggregate of the new hires comparable wages compared to the prior year. In other words, if the aggregate wages paid out are higher than comparable wages during the year, the companies concerned have indeed incurred higher personnel expenses. Tax incentives are thus granted because it improves the business environment and it is the purpose of this legislation. 3. Tax incentive effects The first paragraph of Article 36-2 of the Act for Development of Small and Medium Enterprises provides deductions of business income taxes during the year to qualified SMEs at an amount equivalent to 130% of the incremental wages paid to new headcounts who are Taiwanese nationals. The deductible amount is equivalent to 150% of the incremental wages if new headcounts are Taiwanese nationals below 24 years old. (II) Tax incentives for companies that increase salaries Companies are subject to the effect of changes in the external factors such as global supply and demand on the international market, as well as the domestic business environment as a result of risk aversion from investors and expectation from customers. These uncertainties associated with investments and the rising prices for consumers will suppress the wage levels in Taiwan. This the reason why the second paragraph of Article 36-2 of the Act for Development of Small and Medium Enterprises grants tax deductions for the companies who increase salaries, to encourage companies share earnings with employees and enhance private-sector consumption. SMEs may deduct their business income taxes payable during the year up to 30% of salary increase for existing entry-level employees who are Taiwanese nationals, not as a result of statutory requirement for basic wage adjustments. 1. Taxpayers The tax incentives are applicable to SMEs as defined by the Regulations for the Tax Preferences Provided to Small and Medium-sized Enterprises on Additional Wage Payment and based on the same economic indicators previously mentioned. 2. Qualification for tax incentives (1) Definition of entry-level employees The object of taxation under this act is the enterprise's average wage payment to the entry-level employees. The entry-level employees referred to in this act are authorized by the "Small and medium-sized enterprise employee salary increase, salary deduction act " that refers to employees of local nationality with an average monthly recurring salary below nt $50,000[8] whose were entered into indefinite employment contracts with SMEs. Through such conditions, the effect of tax concessions will be concentrated on promoting the salary level of grassroots staff and helping enterprises to cope with changes in the industrial environment. (2) Average salaries The salaries to entry-level employees refer to the basic salaries, fixed allowances and bonuses paid on a monthly basis. Payment-in-kind shall be discounted based on the actual prices and included into the regular salaries. Meanwhile, regular salaries should be calculated with annualized averages, as this legislation seeks to boost salary levels. The regular salaries to entry-level employees during the year are estimated with the monthly number of entry-level employees during the same year. Only when the average basis salaries during the year are higher than those in the prior year can the tax incentives be applicable. 3. Tax incentive effects Applying this article, SMEs can deduct their business income taxes each year up to 130% of salary increase for existing entry-level employees who are Taiwanese nationals, which are not as a result of statutory requirement for basic wage adjustments. However, it is not allowed to double count the increased personnel expenses for new headcounts applicable to the first and second paragraphs of the same article. V. Conclusions The funding scales and relatively weak financial structures are the factors that led SMEs be susceptible influenced by supply change dynamics and business cycles. To the extent that is suppressing the flexible in capital utilization for SMEs, also influencing on the sustainability of SMEs. Differ from government subsidies require budgeting, reviewing and implementations, there are complications regarding the allocation of administrative resources. Therefore, it is important to plan for tax incentives in order to stimulate R&D, innovation and job creation by SMEs and ultimately make SMEs more competitive. The tax incentives to SMEs amended in 2016 by the Small and Medium Enterprise Administration are known for the following: (I) The lowering of thresholds for tax reductions of R&D expenses in order to encourage SMEs to invest in R&D activities with a “certain degree” of innovativeness and enhance the momentum for SMEs to upgrade and transform themselves; (II) Deferral the income taxations on the transfer of intellectual properties for equity, in order to encourage application and utilization of such intellectual properties, provide incentives for R&D programs or innovations by individuals and SMEs. This also creates a catalyst for industry upgrade; (III) Tax deductions for the employment of new headcounts or the increase of employee wages during the time the economic indicators have reached a certain threshold and based on the health of the investment environment. This is to encourage company investments and capital increases in Taiwan and mitigate the volatility of economic cycles, in order to get ready for business improvement. The above tax incentive programs, i.e. tax deductions for R&D and innovations; deferral of taxations on the transfer of intellectual properties for equity; tax deductions for the hiring of new headcounts and the increase of employee salaries, are meant to boost the investment from SMEs and the competitiveness of SMEs. The Act for Development of Small and Medium Enterprises seeks to reduce tax burdens of SMEs actively investing for their future and competitive advantages. Tax incentives help to mitigate the adverse effect of the economy on the business environment. It is also the fostering of the sources of business income tax revenues for the government. This is the very purpose of the Act for Development of Small and Medium Enterprises. [1]White Paper on Small and Medium Enterprises in Taiwan, 2018, p21 (November 9, 2018) published by the Ministry of Economic Affairs [2]Pursuant to the authorization conferred by Article 35 of the Act for Development of Small and Medium Enterprises, the Ministry of Economic Affairs has announced the Regulations Governing the Reduction of Expenditures for Small and Medium Enterprises Research and Development as Investment. [3]Article 2 on the definition of SMEs. The abovementioned criterion is universally applicable to the Act for Development of Small and Medium Enterprises. It also applies to the eligibility of tax incentives to be introduced in this paper unless otherwise specified. [4]Official Letter Economic-Business No. 10304605790, Ministry of Economic Affairs [5]Official Letter Taiwan-Finance No. 10300207480, Ministry of Finance [6]“Assessment of the Taxations under Article 35, Article 35-1, the first paragraph and the second paragraph of Article 36-2, the Act for Development of Small and Medium Enterprises” published by the Small and Medium Enterprise Administration, Ministry of Economic Affairs, pages 15-17, https://www.moeasmea.gov.tw/files/2670/93B9AF54-84E2-4293-A5CA-EA7DD9FAA05A(most recently browsed date September 9, 2019). [7]Order of Interpretation Economics-Business No. 104004602510 from the Ministry of Economic Affairs: “Second, on the day when the economic indicator has reached the threshold, the paid-in capital of the new business should be at least NT$500,000 and there is no need to instill additional capital during the period when tax incentives are applicable. For existing businesses, there is no limitation on the number of capital increases during the applicable period. So long as the cumulative increase in capital reaches NT$500,000 and new employees are hired during the same fiscal year or during the prior fiscal year.” [8]Paragraph 1, Article 2 of the Regulations for the Tax Preferences Provided to Small and Medium-sized Enterprises on Additional Wage Payment
- The amendment of the Taiwanese Personal Data Protection Act
- Impact of Government Organizational Reform to Scientific Research Legal System and Response Thereto (1) – For Example, The Finnish Innovation Fund (“SITRA”)
- Legal issues of Third-Party Payment in Taiwan
- The Demand of Intellectual Property Management for Taiwanese Enterprises
- Recent Federal Decisions and Emerging Trends in U.S. Defend Trade Secrets Act Litigation
- Blockchain in Intellectual Property Protection
- Impact of Government Organizational Reform to Research Legal System and Response Thereto (2) – Observation of the Swiss Research Innovation System
- Taiwan's Approach to AI Governance